Transfer Pricing Risks: When Intercompany Pricing Becomes a Governance Problem
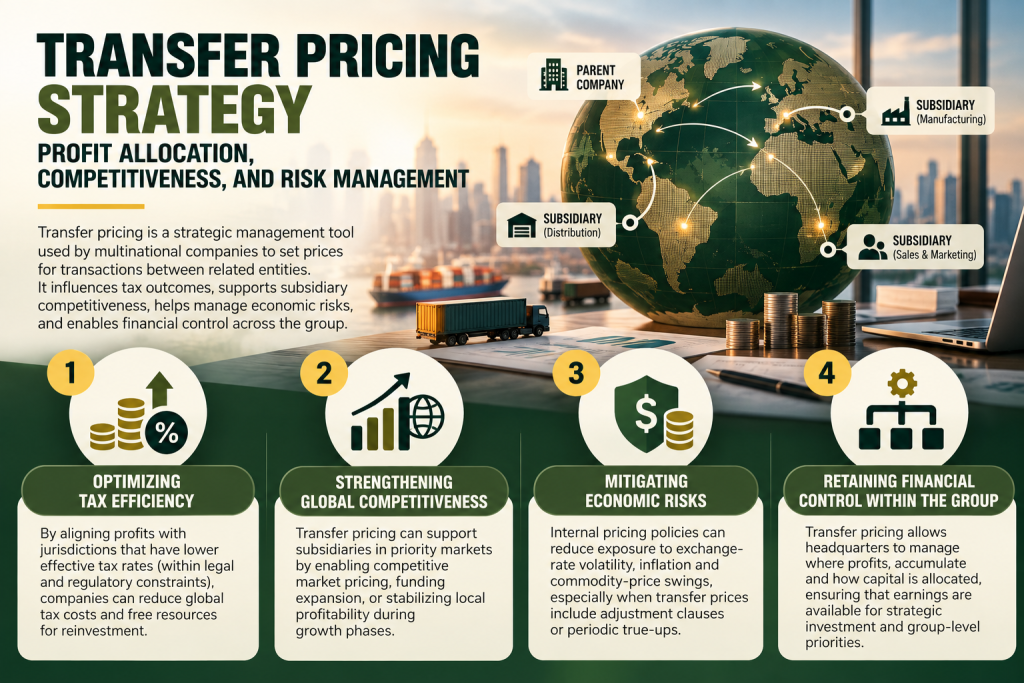
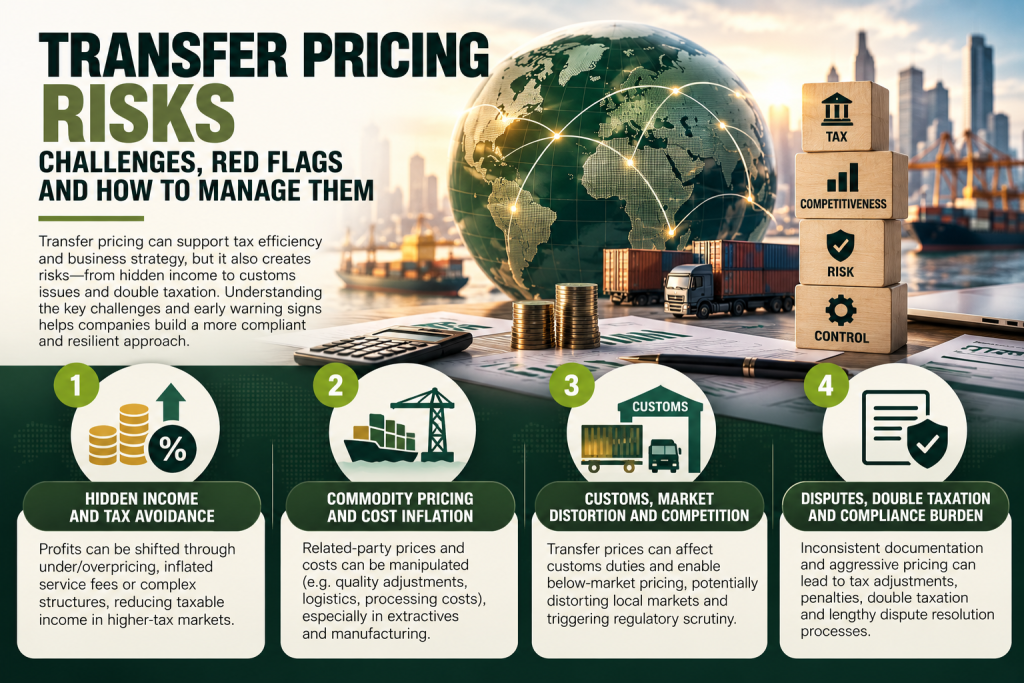
Transfer pricing risks arise when the prices and terms applied to transactions between related companies are not adequately supported, documented, or governed. Although transfer pricing is often treated primarily as a tax compliance issue, weaknesses in intercompany pricing can also expose broader problems in corporate oversight, financial reporting, accountability, and risk management.
This article examines how intercompany pricing decisions can become governance challenges, particularly when commercial objectives, tax considerations, and internal controls are poorly aligned. It explores the importance of the arm’s length principle, defensible documentation, clear decision-making responsibilities, and effective oversight in managing related-party transactions.
Transfer Pricing Risks: When Intercompany Pricing Becomes a Governance Problem Read More »