
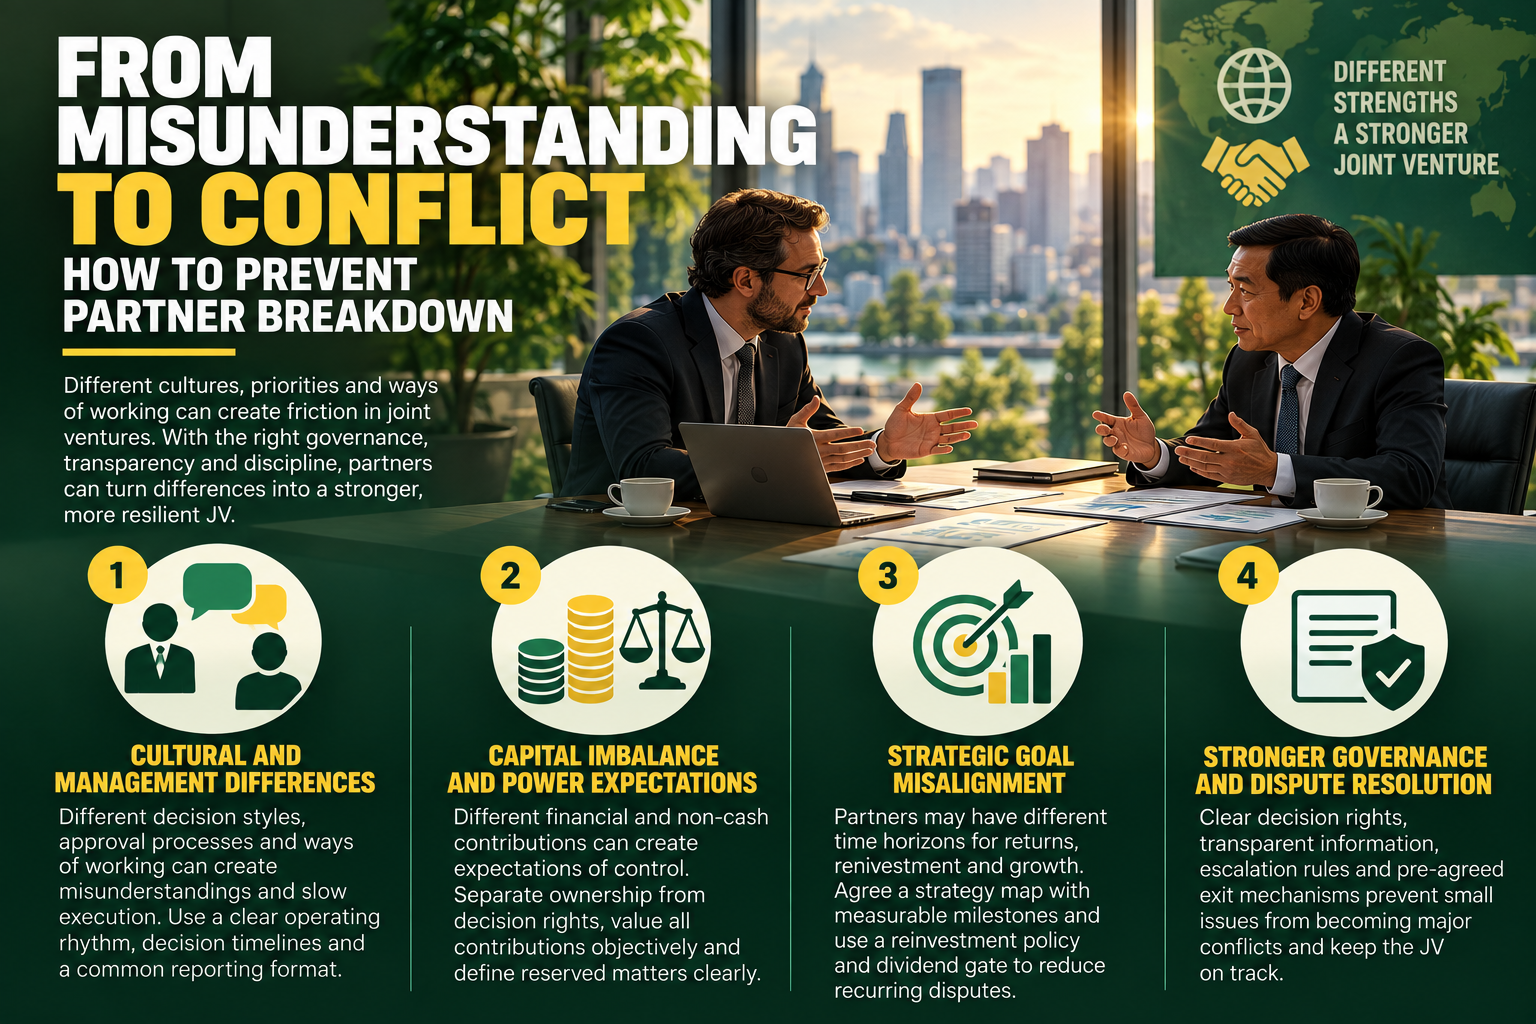
From Misunderstanding to Conflict: How to Prevent Partner Breakdown
Joint ventures between foreign and domestic partners combine complementary strengths, but differences in management culture, control expectations and strategic horizons can gradually undermine cooperation. Preventing JV breakdown requires clear decision rights, common reporting, objective financial rules and mechanisms for resolving disagreements before mistrust becomes institutionalized.
Foreign and domestic partners establish joint ventures because each side possesses something the other cannot easily replicate. The foreign partner may contribute capital, proprietary technology, international brands, global operating systems and access to multinational customers. The domestic partner can contribute market knowledge, regulatory relationships, distribution networks, local talent and the practical ability to operate within the host country’s commercial environment.
These differences create the economic rationale for the partnership, but they also create its vulnerabilities. Partners may have different management cultures, financial expectations, decision-making styles and definitions of acceptable risk. The same differences that create complementary value can eventually become sources of joint venture partner conflict.
Most JV relationships do not deteriorate because of one dramatic disagreement. Problems usually accumulate through delayed approvals, disagreements over recruitment, inconsistent reporting, disputes over pricing or suspicion that one partner is receiving more economic value than the other. Individually, these issues can appear minor, but collectively they can change how each shareholder interprets the other’s behavior.
Once trust begins deteriorating, governance behavior often changes as well. Partners request additional approvals, scrutinize transactions more aggressively and become reluctant to delegate authority. The JV gradually moves from cooperation toward control—and greater control often makes the operating company slower and less competitive.
The resulting performance deterioration can then reinforce the original mistrust. Preventing this cycle requires more than good personal relationships between shareholder representatives. Successful JVs institutionalize cooperation through governance, financial controls, common information and predetermined mechanisms for resolving disagreement.
Cultural and Management Differences Can Quietly Damage Execution
Cross-border JVs frequently combine very different approaches to management. A multinational parent may emphasize formal procedures, centralized approvals, extensive documentation and strict compliance requirements. A domestic partner may place greater emphasis on speed, relationships and flexibility in responding to local customers or regulators.
Neither approach is automatically superior. Formal controls can reduce compliance and financial risks, while local flexibility can be essential in markets where customers expect rapid decisions and administrative processes are less predictable. Conflict begins when each partner interprets a different management style as evidence that the other side is incompetent, obstructive or untrustworthy.
The foreign shareholder may interpret informal decision-making as a lack of discipline. The local partner may interpret multiple approval layers as headquarters bureaucracy that prevents the JV from responding to the market. Management meetings then become arguments about process rather than discussions about commercial results.
A predefined operating rhythm can reduce this friction. Weekly management meetings can address immediate operational issues, monthly reviews can focus on financial and commercial performance, and quarterly board meetings can deal with strategy and major investment decisions. Each governance level receives a clear purpose rather than becoming another forum for repeating the same disagreements.
Decision timelines are equally important. If procurement approvals should normally be completed within 72 hours and exceptional pricing requests within 48 hours, both shareholders know when an issue has become overdue. A defined decision clock converts frustration into a measurable governance problem.
Partners should also use the same reporting architecture. Revenue, EBITDA, working capital, market share, production efficiency and other important KPIs should have agreed definitions and data sources. When each shareholder arrives with different calculations, even discussions about basic performance can become disputes about whose numbers are correct.
Some cross-border JVs can also benefit from a small integration function, particularly during their early years. A bilingual or cross-cultural team led by executives such as the CFO or COO can standardize reporting, meeting procedures and approval workflows. The objective is not to eliminate cultural differences; it is to prevent those differences from disrupting execution.
Capital Contributions Should Not Create Ambiguous Power
Ownership and control represent another fundamental source of tension. A foreign investor financing most of the project may naturally believe that its greater financial exposure should produce stronger control rights. The local partner may respond that capital alone does not capture the value of land, licenses, distribution networks, regulatory knowledge or relationships contributed to the venture.
Both arguments can contain economic logic. The governance problem appears when these different expectations are never explicitly reconciled. A 70% financial contribution does not automatically answer every question about how a JV should be governed.
Board representation is usually one of the first areas where this tension becomes visible. Partners need to determine whether voting rights follow equity ownership directly, whether particular decisions require both shareholders’ consent and which matters can be decided by management without shareholder involvement.
Executive appointments create another potential power struggle. One parent may expect to appoint the CEO because it contributes most of the capital, while the other may insist on controlling the CFO, procurement or government-relations functions. If positions become proxies for shareholder power rather than clearly defined corporate responsibilities, management can fragment into competing camps.
A better approach is to separate ownership economics from governance rights deliberately rather than allowing the relationship to develop informally. Financial control, operational authority and strategic veto rights can be allocated differently when the commercial rationale supports doing so.
Non-cash contributions also need credible valuation. Land rights, licenses, distribution networks, customer relationships and regulatory access can have substantial economic value even though they do not appear as a cash transfer into the JV’s bank account. Treating the local partner’s contributions as “soft” while treating foreign capital as the only real investment can create resentment from the beginning.
Consider a structure in which the foreign investor contributes 70% of the capital while the domestic shareholder provides land, market access and critical local capabilities. The foreign parent might receive enhanced financial reporting and audit protections, while the local partner receives clearly defined responsibility for regulatory liaison and stakeholder management. The precise allocation will differ between ventures, but explicit asymmetry is usually easier to manage than ambiguous equality.
Strategic Misalignment Creates the Time-Horizon Problem
Even partners that agree on how to launch a JV may eventually disagree about what success should look like. The foreign parent may prioritize cash generation, return on invested capital and dividend repatriation because headquarters evaluates the investment against other opportunities in its global portfolio. The domestic partner may place greater emphasis on market share, capacity expansion, employment and long-term local positioning.
These objectives can coexist during the early growth phase. The disagreement becomes visible when the JV generates meaningful cash or requires another large investment. The first major decision about expansion often reveals whether the partners actually share the same time horizon.
Imagine that a successful manufacturing JV is operating near capacity. The local shareholder wants another production line because demand is growing and additional capacity could strengthen market leadership. The foreign shareholder faces pressure to improve group cash flow and prefers distributing earnings rather than committing additional capital.
Neither position is necessarily irrational. But if the JV agreement provides no objective framework, management becomes trapped between incompatible shareholder instructions. Capex can be postponed, suppliers receive uncertain forecasts and competitors gain time to respond.
A three-year strategy map can reduce this risk by establishing measurable milestones in advance. Capacity utilization, market coverage, product quality, customer retention and profitability targets can determine when expansion or additional investment becomes appropriate. Strategic decisions are then connected to previously agreed conditions rather than whichever shareholder currently has greater negotiating leverage.
Dividend policy should follow the same principle. A dividend gate can require minimum liquidity, approved capex funding, covenant compliance and other conditions before cash is distributed. Once those requirements are satisfied, an agreed distribution formula can apply.
Reinvestment should also be linked to measurable objectives. Additional capital can depend on utilization levels, service coverage, customer commitments or return thresholds rather than general arguments about growth. Objective financial rules cannot eliminate strategic disagreement, but they can prevent the same disagreement from being renegotiated every quarter.
Governance Must Stop Disagreement From Becoming Breakdown
The most dangerous stage of JV conflict occurs when disagreement becomes institutionalized. At this point, shareholders no longer evaluate individual decisions independently; each decision is interpreted through a broader assumption that the other partner is attempting to gain control or extract disproportionate value.
Information becomes especially important during this stage. If one shareholder believes the other has privileged access to management or operating data, suspicion increases rapidly. Both parents should receive consistent information through formal governance channels rather than relying on informal relationships with executives they appointed.
Clear delegated authority also protects management from shareholder conflict. Routine pricing, procurement, recruitment and operating expenditure should remain within management’s authority when they fall inside the approved strategy and budget. Shareholder approval should focus on reserved matters such as major investments, borrowing, acquisitions, related-party transactions and fundamental changes in strategy.
Conflict-of-interest procedures are particularly important because shareholders may also transact with the JV. One parent might supply technology, components or management services while the other controls distribution or real estate. Related-party arrangements should therefore be benchmarked and approved through transparent procedures rather than negotiated informally.
Escalation rules provide the next layer of protection. An unresolved management issue can move to the JV board and subsequently to designated senior executives from each parent, with defined deadlines at every stage. Escalation should be a governance process, not an emotional reaction to a deteriorating relationship.
True deadlocks require predetermined solutions. Depending on the JV structure, these can include mediation, independent expert determination, arbitration or mechanisms allowing one shareholder to buy the other’s interest. Exit provisions should define valuation methodology, transfer restrictions, treatment of intellectual property and operational arrangements during transition.
Planning for exit does not mean partners expect the venture to fail. It recognizes that strategic circumstances can change even when the original investment was rational. A well-designed exit mechanism can actually stabilize a JV because neither shareholder needs to create an operating crisis simply to escape an unsustainable relationship.
The ultimate objective is to keep shareholder disagreements away from customers, employees and daily operations for as long as possible. Once parent conflict begins disrupting ordinary commercial decisions, the JV’s deteriorating performance can become additional evidence each shareholder uses against the other.
Joint venture partner conflict rarely begins with the dispute that ultimately breaks the relationship. It develops through repeated smaller disagreements about approvals, information, control, investment and economic value. Each unresolved issue makes the next disagreement more difficult because the partners gradually stop assuming good faith.
Governance must therefore intervene before that cycle becomes self-reinforcing. Common KPIs reduce arguments over facts, decision deadlines reduce frustration, clear authority protects operating speed and objective dividend and investment rules prevent recurring financial disputes. These mechanisms transform expectations into processes.
Partners should also recognize that different objectives are not automatically evidence of disloyalty. A multinational parent and a domestic shareholder can legitimately have different capital constraints, strategic horizons and operating cultures. Successful JV governance does not require identical interests; it requires a system capable of managing different interests without damaging the company.
That system should include an orderly path for situations in which alignment cannot be restored. Escalation, mediation, deadlock procedures and exit mechanisms protect the operating business from becoming the weapon through which shareholders negotiate with each other. The objective is continuity even when the partnership itself becomes difficult.
The strongest JVs consequently combine operational clarity, financial transparency, balanced control and predetermined conflict-resolution mechanisms. Personal trust remains valuable, but it should reinforce governance rather than substitute for it.
Ultimately, the decisive question is not whether foreign and domestic partners will disagree. They will. The real test is whether the JV’s governance converts disagreement into a decision—or allows misunderstanding to become mistrust, mistrust to become conflict and conflict to become breakdown.